Once you receive your profit and loss statement, whether it has been prepared by your accountant or generated from your accounting software, you can see how much your business has earned, what it has spent and whether it has made a profit or loss.
But what can those figures actually tell you about the performance of your business? If you only look at the final profit or loss without understanding how the figures relate to one another, you may miss important signs about your sales, costs, margins and profitability.
In this guide, we explain what a profit and loss statement can tell you about your business, how to read the figures, what to look for when comparing your results and what the statement cannot tell you.
Key Takeaways
- A profit and loss statement is a financial report that shows your business’s income, expenses and profit or loss over a specific period.
- Your profit and loss statement can show whether your sales are profitable, direct costs are increasing, overheads are putting pressure on profit and your business is growing profitably.
- Reading your P&L from top to bottom helps you see how changes in sales, direct costs and overheads affect your profitability.
- Working with our trained accountant can help you prepare your profit and loss statement, understand what the figures mean and use them to make better-informed business decisions.
 What Is a Profit and Loss Statement?
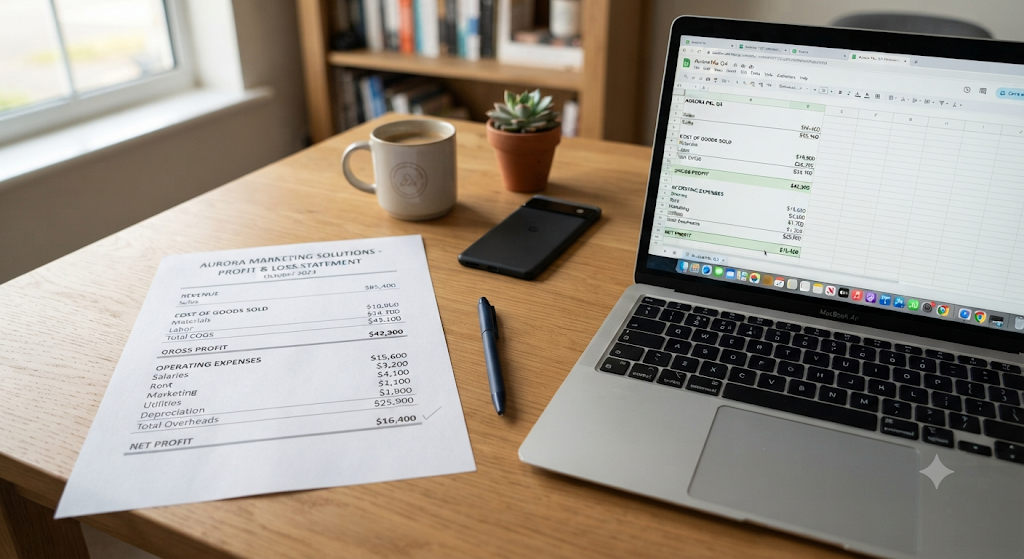
A profit and loss statement, also known as an income statement, is a financial report that shows your business’s total income, expenses and profit or loss over a set period of time.
It is one of the key financial documents you need to understand how well your business is performing.
What Does a Profit and Loss Statement Show?
An income statement is made up of certain key figures, which including:
- Turnover or Sales: Turnover is the total income your business earns from selling its products or services before expenses are deducted.
- Cost of Sales: These are the costs involved in purchasing the products or delivering the services your business offers. For example, the cost of raw materials, production labour and packaging.
- Gross Profit: Gross profit is the amount you have left after subtracting your cost of sales from your turnover.
- Overheads: Overheads, also known as operating expenses, are the costs of running your business that are not included in your cost of sales. For example, rent, insurance, office expenses and accounting fees.
- Operating Profit: Operating profit, also known, as Earnings Before Interest and Tax (EBIT), is the profit your business makes after deducting its cost of sales and operating expenses, but before interest and tax.
- Other Income and Expenses: These are income or expenses that are not part of your business’s normal operating activities. For example, interest received, interest paid, or gains and losses from other activities.
- Profit Before Tax: This is the profit your business makes after all income and expenses have been accounted for, but before tax is deducted.
- Tax: This is the amount of tax charged on your business’s profit for the accounting period.
- Net Profit or Loss: This is the profit your business makes after all income, expenses and tax have been accounted for. If your total expenses are greater than your income, the result is a net loss.
What Can Your P&L Tell You About Your Business?
Your P&L is more than a record of what your business earned and spent. When you compare the figures over time, it can help you understand what’s driving your profits, where costs are increasing and whether your growth is actually improving your bottom line.
Here are some of the key things your P&L can tell you:
Are Your Sales Actually Profitable?
Your P&L statement can show whether the sales you generate are producing enough gross profit after the direct costs of making or delivering what you sell.
This matters because increasing sales does not necessarily mean you are making more profit. For example, a manufacturer may win more orders but see little improvement in gross profit if material, production or subcontracting costs rise at the same time.
Looking at your gross profit and gross profit margin can therefore highlight whether the profitability of your sales is changing.
If it shows a falling margin, it may indicate that selling prices, cost of sales or the mix of products being sold needs closer attention.
Are Your Direct Costs Increasing?
Your P&L can show whether the costs directly associated with generating your income are increasing and whether they are taking a larger share of your sales.
This is particularly important when your sales are growing. If turnover increases but cost of sales rises faster, your gross profit margin will fall.
ACCA notes that changes in gross profit margin can result from changes in selling prices, sales volume or cost of sales.
For a manufacturing business, this could highlight rising material, production or subcontracting costs that are reducing the margin generated from sales.
The P&L therefore gives you an early indication that your direct costs may need investigation, rather than simply showing that your total costs have increased.
Are You Charging Enough?
A profit and loss statement cannot tell you what price to charge. However, it can show whether the prices you are currently charging are generating the margin your business needs.
For example, if the cost of materials or production increases while your selling prices stay the same, your gross profit margin will fall. This can be a sign that your prices need to be reviewed.
However, pricing decisions should also take account of customer demand and what competitors are charging.
So, the P&L gives you useful financial evidence for that review. You can see how much gross profit you are generating from your sales and whether that margin is being squeezed by rising costs.
Are Your Overheads Growing Too Quickly?
Overheads can increase without being a problem. But a P&L can tell you whether those costs are taking an increasing share of the income your business generates and putting pressure on operating profit.
For example, if costs such as payroll, premises, software, insurance or professional fees increase while income and gross profit remain relatively stable, operating profit will be squeezed.
To tell whether the change is temporary or part of a longer-term trend, you’ll have to compare these figures over different periods.
Also, the operating profit margin from your profit and loss statement can provide another useful measure.
Which Months Are Profitable?
If you review your P&L by month, you can see when the business is making a profit and when it is making a loss.
This can reveal patterns that an annual figure would hide, such as quieter months, seasonal peaks or periods when costs temporarily outweigh income.
For example, a business might record a £2,000 loss in January, a £1,000 profit in February and a £5,000 profit in March. The monthly P&L shows how profitability changes from one period to another.
Is Growth Actually Increasing Profit?
A profit and loss statement is useful for distinguishing sales growth from profitable growth.
It lets you compare turnover with gross profit, operating profit and net profit across different periods, so you can see whether an increase in sales is also leading to an increase in profit.
For example, if turnover rises but operating profit stays the same or falls, the business is generating more sales without improving its profitability.
The figures can also show where that change is occurring. If turnover has increased but gross profit has grown more slowly, cost of sales may be taking a larger share of income.
If gross profit has increased but operating profit has not, rising overheads may be absorbing the additional gross profit.
Are You Performing as Expected?
Your P&L shows what your business actually achieved. When you compare those results with your budget or forecast, you can see whether the business is performing as expected.
For example, if you expected £50,000 in turnover for a period but your P&L shows £42,000, the £8,000 difference gives you a reason to investigate. You may need to look at sales volumes, pricing or other factors affecting revenue.
The same applies to costs and profit. Once you compare actual figures with what you expected, it can help you identify where performance has differed from plan and decide whether anything needs to change.
What Your P&L Statement Cannot Tell You
A profit and loss statement gives you an important view of your business, but it does not tell you everything you need to know about its financial position.
Here’s what you can’t know from your income statement:
How Much Cash You Have Available
Making a profit does not necessarily mean you have enough cash available to pay your bills.
The P&L records income and expenses for the period, but it does not show how much cash is actually available in your bank account. On the other hand, cash flow tracks money coming into and going out of the business.
For example, you may have made sales and recognised the income in your P&L, but if customers have not paid their invoices yet, that income may not have been received as cash.
Your P&L can therefore show that you have made a profit without showing how much money you currently have available to spend.
What Your Business Owns and Owes
The P&L does not show your business’s complete financial position. It does not tell you the value of your assets, how much you owe or how much equity the business has. These are shown on the balance sheet.
This matters because a business can report a profit while still having significant liabilities or a weak financial position.
What Your Profit Will Be in the Future
A P&L tells you what happened during the period it covers. It cannot tell you with certainty what your income, costs or profit will be in the months ahead.
Future performance requires forecasts and budgets based on assumptions about sales, costs and other factors.
The historical P&L can provide useful evidence for those forecasts, but it is not a forecast itself. For an accurate cashflow forecast, you can work with our trained accountant, Tiba Al-Khalidy.
Where All Your Profit Is Coming From
A standard profit and loss statement may show the business’s overall income and profit without showing which individual products, customers, projects or services are generating that profit.
You may need a more detailed analysis to identify which parts of the business are most or least profitable.
This is particularly relevant if you have different product lines, services or customer groups.
How to Read a Profit and Loss Statement
When reading a profit and loss statement, work through the figures from top to bottom rather than focusing only on the final profit or loss.
Start With Turnover
Start by looking at your turnover for the period covered by the P&L. Compare it with a previous period or your budget to see whether sales have increased, decreased or remained broadly the same.
A change in turnover can have different causes. An increase could come from selling more products, increasing your prices or winning larger orders, while a fall could indicate lower sales volumes or a quieter trading period.
Check Your Gross Profit
Next, look at how your gross profit has changed in relation to your turnover. If sales have increased but gross profit has not increased by a similar amount, your direct costs may be taking a larger share of your sales.
For example, a manufacturing business may win more orders and increase its turnover, but if the cost of materials, production or subcontracting rises at the same time, the increase in sales may not translate into much additional gross profit.
This comparison helps you see whether higher sales are actually generating more profit after the direct costs of producing what you sell.
Look at Your Gross Profit Margin
Now compare your gross profit margin with previous periods to see whether the proportion of sales left after direct costs is improving or falling.
If the margin is falling, look at what has changed in your selling prices, sales mix or direct costs. For example, a manufacturer may see its margin fall because material or production costs have increased while selling prices have remained unchanged.
A falling margin can therefore highlight a change in the profitability of your sales that may need further investigation.
Review Your Overheads
Once you have looked at your gross profit margin, review your overheads and compare them with previous periods.
Look for costs that have increased significantly, such as payroll, premises, insurance, software or professional fees. The key question is whether those increases are putting pressure on your operating profit.
For example, if your gross profit has increased but your operating profit has fallen, rising overheads may be absorbing the additional gross profit.
Check Your Operating Profit
Now look at your operating profit and compare it with previous periods.
If your gross profit is increasing but operating profit is falling, it suggests that your overheads are taking up more of the additional gross profit.
If both gross profit and operating profit are improving, it indicates that the business is retaining more profit after its operating costs.
Look at Net Profit or Loss
Finally, look at the net profit or loss for the period and compare it with previous periods.
If the figure has improved, consider what has driven the change. For example, if profit has fallen despite higher turnover, the earlier figures in the profit and loss statement, can help you identify whether the change is linked to lower margins, higher overheads, or other income and expenses.
Compare the Results
Once you have worked through the P&L, compare the figures with previous periods, your budget or your forecast.
Look for changes between turnover, gross profit, margins, overheads and operating profit. For example, if turnover has increased but gross profit has barely changed, your direct costs or pricing may need attention.
If gross profit has increased but operating profit has fallen, rising overheads may be absorbing the additional gross profit.
Comparing the results helps you know what is driving changes in your profitability and where your business may need attention.
How Often Should You Review Your Profit and Loss Statement?
For many small businesses, reviewing your profit and loss statement monthly provides a useful way to keep track of financial performance and spot changes early.
However, the right frequency depends on the size and nature of your business, with some smaller businesses finding a quarterly review more appropriate.
Regular reviews allow you to monitor changes in sales, gross profit, overheads and operating profit rather than waiting until the end of the financial year to see how the business has performed.
If your business has significant seasonal changes, fluctuating costs or tighter profit margins, you may benefit from reviewing your P&L more frequently.
The important thing is to review it often enough to identify changes in performance and investigate anything that is different from previous periods or your budget.
A consistent review of your profit and loss statement gives you better information for managing the business and making decisions based on what is actually happening, rather than relying only on your year-end figures.
Also Read:
- Why Small Businesses Have Cash Flow Problems
- VAT Registration UK: A Complete Guide for Small Businesses
What Should You Do If Your P&L Shows a Problem?
If your P&L highlights a problem, the next step is to understand what is causing it before deciding what to change.
You may need to review your pricing, investigate rising direct costs, analyse your margins, control overheads or look more closely at the profitability of different products, services or customers.
If the issue is affecting your cash position, you may also need to strengthen your cash-flow planning.
The right action depends on what the figures are showing, but the purpose of reviewing your P&L is to identify issues early enough to do something about them.
Work With Surrey Accountancy to Prepare and Understand Your Profit and Loss Statement
A profit and loss statement can show where your business is making money, where costs are putting pressure on profit and whether your growth is actually profitable. But preparing and interpreting the figures can be difficult when you’re focused on running your business.
At Surrey Accountancy, we can prepare your profit and loss statement and help you understand what the figures are telling you, so you can make more informed decisions about your business.
If you need help with your P&L, speak to our team today.
Contact Surrey Accountancy Today
Frequently Asked Questions
How Do You Get a Profit and Loss Statement?
A P&L statement is prepared from your business accounting records, including your sales, income and business expenses, over a specific period. If you use accounting software, you can usually generate a P&L report from your recorded transactions, while an accountant can prepare one from your financial records.
What are Some Red Flags in a P&L?
Common red flags of a profit and loss statement include falling revenue, shrinking gross or net profit margins, expenses increasing faster than sales, or repeated losses.
Comparing your P&L with previous periods can help you spot unusual changes and investigate what is driving them.
What is the Main Purpose of the Statement of Profit or Loss?
The main purpose of a P&L is to show your business’s income, costs and resulting profit or loss over a particular period. It helps you understand how your business has performed and whether it is generating enough profit from its operations.
What are the Five Key Components to a P&L Statement?
The five key components can be grouped as revenue, cost of sales, gross profit, operating expenses and net profit or loss. These figures show how much you earned, what it cost to generate that income, what remained after those costs and your final profit or loss
What are the Four Main Types of Financial Statements?
The four main financial statements are the statement of profit or loss, balance sheet, cash flow statement and statement of changes in equity. These statements show business performance, financial position, movements in cash and changes in owners’ equity.